Selling a company or bringing in an investor: what supports the proposed value, and which assumptions could a buyer challenge?
Independent advisory firm · Poland
Business valuation in Poland
SIPEX provides business valuation in Poland for owners, shareholders and investors planning a sale, a shareholder settlement or succession. We value businesses and shareholdings at an agreed date and for a defined purpose. You receive a report explaining the valuation methods, calculations and assumptions behind the result.
You may need to value an entire business, the equity of a company or a particular shareholding. We establish the scope before choosing the methods, so the report addresses the decision you need to make.
Discuss your valuation with SIPEX
Call: +48 602 653 234Indicative feeFrom EUR 2,000 netPlus VAT. We confirm the fee after reviewing the scope.TimingA few days to several weeksDepending on complexity and the available information.
SIPEX experienceOver 100 businesses a yearValuing businesses since 1996.
Service areaPolandDiscussions and document exchange also handled remotely.
When you need a business valuation
A valuation gives you an analytical basis for decisions about ownership and investment. The questions differ with the situation:
Buying a business or shares: how do earnings, investment needs and risks affect the value of the proposed acquisition?
Settling with a shareholder: what is being transferred, what rights does the shareholding carry, and how does this affect the settlement?
Succession and family ownership changes: what is the value of the business or shares being transferred, including shares contributed to a Polish family foundation?
If your valuation concerns a contribution in kind, reorganisation, financial reporting or a legal dispute, explain the intended use at the outset. This also applies to internal investment decisions and tax-related assignments, including transfer pricing. We establish the required basis of value, documentation and scope for that particular matter.
Why work with SIPEX?
SIPEX is an independent Polish advisory firm specialising in business and share valuation, with a focus on small and medium-sized enterprises. We value over 100 businesses each year and have been carrying out valuations since 1996. We work with clients across Poland, with discussions and document exchange also handled remotely.
You work directly with the analyst. From the first conversation to the final report, you can discuss the company’s circumstances, financial records and assumptions with the person carrying out the valuation.
We value the business and its assets in-house. Our team combines business analysts with specialists in real estate, machinery and intangible assets. We carry out the necessary work within SIPEX, which helps coordinate the analysis and keep confidential documentation within the team.
We help with the financial side of ownership changes. Our work includes financial models, analysis of shareholder repayment options and support in negotiations. Where a sale requires an active search for buyers, we work with specialist partners and agree responsibilities at the outset.
Our own analytical tools support data processing and consistent reporting. The analyst remains responsible for choosing the methods, assessing the assumptions and interpreting the result.
The practice is led by Michał Krzempek, who has more than 12 years of experience and is a court expert in business valuation in Kraków and Warsaw. His work includes explaining and defending valuation reports before courts and prosecutors. He is a SIPEX board member, a property valuer (licence no. 6195), a member of SBWPwP and a lecturer on postgraduate business valuation courses.
What exactly are you valuing?
The value of the operating business, the value attributable to shareholders and the value of a specific stake answer different questions.
Enterprise value describes the value of the operating business to its capital providers. Equity value is the value attributable to shareholders after allowing for the relevant financing claims, cash and other adjustments.
For a share valuation, we also examine the rights and restrictions attached to the holding. A 20% interest in a Polish limited liability company, or sp. z o.o., may differ in value from 20% of the company’s total equity value. Control, transfer restrictions and marketability require assessment; any adjustment needs justification.
We also establish the basis of value: the definition and assumptions under which value is estimated. Market value and value to a particular investor can differ. The valuation date matters because the company’s position and market conditions change.
What you receive in the valuation report
You receive an estimated value, or range of values, with the calculations and reasoning behind it. The report explains:
- what is being valued, for whom, for what purpose and at what date;
- the company’s operations, financial position and factors affecting value;
- the methods, assumptions and calculations used;
- the conclusion on value, limitations and intended use of the report.
Depending on your needs and the available information, we agree whether the assignment calls for a full valuation, a limited valuation or an initial calculation of value. Any restrictions or simplified procedures are explained, together with their effect on how the result can be used.
The report gives you a basis for discussions with a shareholder, prospective buyer or adviser. The eventual transaction price also depends on the terms agreed between the parties.
Polish and international valuation standards
We apply both Polish and international valuation standards. These include the General Principles of Business Valuation (KSWS), published by PFSRM in Poland, and the International Valuation Standards (IVS), issued by the International Valuation Standards Council.
For business and share valuations, the international framework includes IVS 200 — Businesses and Business Interests, alongside the IVS General Standards. We establish the applicable standards at the start and identify them in the report. They guide the scope of work, basis of value, choice of methods, documentation and presentation of the conclusions. Where relevant, we agree reporting requirements under the Polish Accounting Act or IFRS with the recipient or auditor.
How we choose the valuation methods
We select from three main approaches: income, asset-based and market. The choice depends on the purpose of the valuation, the company’s circumstances and the available data. We explain the selection and any material differences between the results.
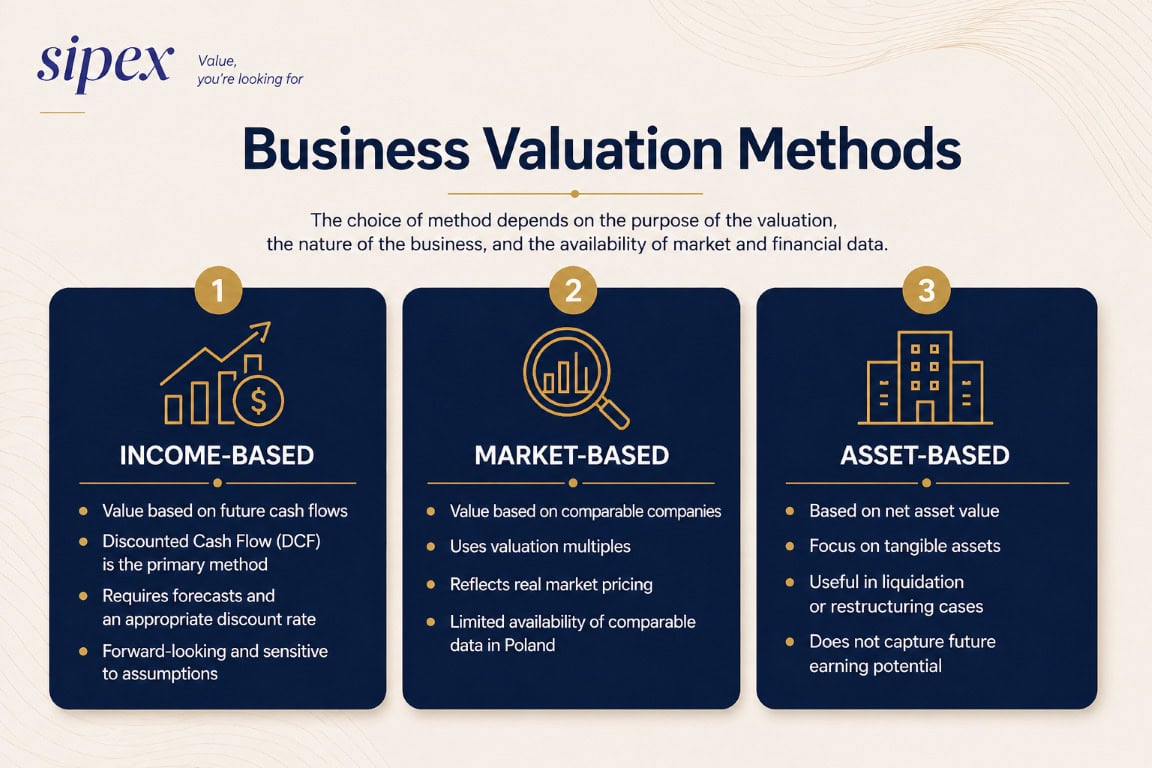 Enlarge the valuation methods overview ↗
Income approach: future cash flows
The discounted cash flow method, or DCF, estimates value from expected future cash flows, discounted to the valuation date at a rate reflecting risk. We examine the assumptions behind revenue, costs, investment and working capital, as well as the discount rate. DCF assumptions also include terminal value; forecasts and discount rates must be consistent. For a stable business, capitalisation of sustainable earnings may be appropriate.
Asset-based approach: assets less liabilities
We assess the value of assets and deduct liabilities, making appropriate adjustments to accounting amounts. This can be relevant for asset-holding businesses or certain restructuring and liquidation situations. For an operating company, we also consider whether asset values adequately reflect its earning capacity.
Market approach: comparable companies and transactions
Market multiples estimate value by applying a ratio observed for comparable companies or transactions to a relevant financial measure of the business. A multiple such as enterprise value to EBITDA — earnings before interest, taxes, depreciation and amortisation — is useful only when the financial measures and businesses are sufficiently comparable. Differences in size, profitability, growth and risk need assessment. We may examine listed-company multiples such as P/E or EV/revenue and completed M&A transactions. Private-company evidence can be limited, so data quality and comparability matter.
What can change the value of a Polish company?
Reported profit is only part of the assessment. Revenue stability and sustainable profitability help assess whether recent results are a reasonable guide to future earnings. Customer concentration, dependence on the owner and future investment needs also affect cash flow and risk. One-off events or related-party transactions may also require adjustments. We also assess management dependence, the industry outlook and market conditions, including interest rates, inflation and regulation, where they affect forecasts or risk.
Brand value, know-how and customer relationships can matter even when they are absent from the balance sheet. We consider their contribution consistently with the chosen method, avoiding double counting benefits already reflected in cash flows. Where the business has foreign-currency revenue or costs, the forecast and discount-rate assumptions must also be consistent.
Documents needed for a business valuation
The initial information usually includes:
financial statements for recent years and current management accounts, or the relevant records where simplified accounting is used;
budgets, forecasts and the assumptions behind planned development;
details of debt, cash, leases, major assets and liabilities;
information about products, customers, important contracts and exceptional events;
the ownership structure, articles of association and rights attached to the shares being valued.
You do not need every document ready before contacting us. Start with the information you have. We identify what can be used and what needs clarification.
If forecasts are required, we discuss the business plans and help develop their financial assumptions. Before confidential documents are shared, we agree how they will be provided and who will have access.
From the first conversation to the final report
Define the assignment.
We discuss the company, the purpose, the valuation date and who will use the report. We agree the scope, fee and timetable.
Review the information.
We analyse the documents, discuss the business with you and clarify gaps or unusual items.
Discuss the draft.
Before completing the report, we discuss whether its description of the business, its circumstances and plans reflects how the company actually operates. This is an opportunity to clarify facts and explain the assumptions.
Deliver and explain the report.
We present the conclusion and explain its assumptions and intended use.
Your knowledge helps us understand the business. The conclusion on value remains based on our independent assessment of the evidence.
For a cross-border matter, tell us which report language and presentation currency you need. We will confirm these when agreeing the scope.
Business valuation costs and timing
Our fees start at EUR 2,000 net, plus VAT. The quotation depends on the number of entities, the complexity of the business and its assets, the quality of the data and the required analysis.
Assignments typically take a few days to several weeks, depending on complexity and the availability of information. We confirm the timetable after reviewing the scope. Tell us about any transaction or settlement deadline in the first conversation.
Selected business valuation references
JSW KOKS S.A.
Wycena udziałów CARBOTRANS Sp. z o.o.
SIPEX przeprowadził kompleksową wycenę udziałów CARBOTRANS Sp. z o.o. na zlecenie JSW KOKS S.A.…
Inare Sp. z o.o.
Wycena przedsiębiorstwa Inare Sp. z o.o.
SIPEX przeprowadził kompleksową wycenę wartości przedsiębiorstwa Inare Sp. z o.o. Prace uwzględniały specyfikę działalności…
P.P.H.U. "GOMAK" Sp. z o.o.
Wycena przedsiębiorstwa PPHU Gomak Sp. z o.o.
SIPEX przeprowadził kompleksową wycenę przedsiębiorstwa PPHU Gomak Sp. z o.o., prowadzącego działalność w branży…
Perio Dens sp. z o.o.
Wycena spółki z branży prywatnych usług stomatologicznych
Realizacja SIPEX: Wycena spółki z branży prywatnych usług stomatologicznych.
Questions about commissioning a valuation
Is a business worth three times its annual profit?
There is no universal profit multiple. The appropriate measure and multiple depend on the business, its growth prospects, risk, investment needs and the market evidence. A rule of thumb can help start the discussion, but it does not replace an analysis.
Does a valuation include due diligence?
A valuation involves reviewing information relevant to estimating value. A full financial, tax or legal due diligence investigation has a separate scope. If you need additional investigation, it should be identified and agreed before work starts.
Can a valuation be used in court or for financial reporting?
The intended use must be established before the assignment begins. A private valuation report and an opinion commissioned by a court have different roles. For reporting or tax matters, the applicable requirements and the recipient’s expectations need to be clarified with the relevant adviser or auditor.
Contact SIPEX
Discuss your business valuation in Poland
Tell us what you need to value, why you need the report and whether you have a deadline. Include the company’s industry, approximate scale and the shareholding involved, if applicable. We will use this information to propose the scope and next steps.
Contact Michał Krzempek on +48 602 653 234 or at m.krzempek@sipex.pl.